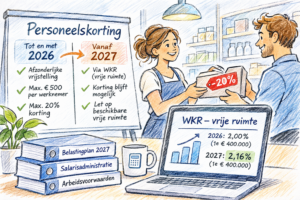
The tax-free employee discount on products and services supplied by the employer is set to disappear from 1 January 2027 under the Dutch Tax Plan 2027. Employers will still be able to provide discounts to employees on a tax-free basis, but in principle the value of the discount will then have to be allocated to the discretionary scope of the Dutch work-related costs scheme (WKR).
The House of Representatives has already adopted the Tax Plan 2027. The measure will only become final once the Senate has also approved the tax package.
How does the current scheme work?
In 2026, a separate exemption still applies to products and services from the employer’s own business.
Subject to the applicable conditions, an employer can provide an employee with a discount of up to 20%, with a maximum tax-free benefit of €500 per employee per calendar year.
This employee discount does not currently reduce the employer’s discretionary WKR budget.
The scheme may, for example, be used by retailers offering staff discounts on their own products, but also by other employers supplying goods or services from their own business to employees.
What changes from 2027?
The government intends to abolish this separate exemption from 1 January 2027.
This does not mean that an employee discount will automatically become taxable salary. An employer may still designate the benefit as final-levy wages under the WKR.
The key difference is that the value of the discount will then use part of the employer’s discretionary WKR budget.
As a result, employee discounts will have to compete with other reimbursements and benefits financed from the same discretionary budget, such as Christmas gifts, gift vouchers and certain staff benefits.
More pressure on the WKR budget
The change can have a noticeable financial impact on employers that make extensive use of employee discounts.
Suppose twenty employees each receive €500 in employee discounts per year. Under the current rules, a total of €10,000 may fall within the separate exemption.
From 2027, that same €10,000 would reduce the employer’s discretionary WKR budget if the employer wants to continue providing the discount tax-free.
If the available discretionary budget is exceeded, the employer is generally liable for an 80% final levy on the excess.
The discretionary scope will increase in 2027
At the same time, the WKR discretionary scope is also expected to become slightly more generous.
In 2026, the discretionary scope amounts to 2.00% of the first €400,000 of the taxable wage bill and 1.18% of the excess.
From 2027, the rate on the first €400,000 is expected to increase to 2.16%.
This gives employers some additional room, but for businesses with significant employee-discount arrangements, the increase may not fully compensate for the disappearance of the separate exemption.
Employment conditions require attention as well
Employers should not only consider the tax consequences.
Employee discounts may form part of an employment contract, staff scheme or collective labour agreement. If an employer wants to reduce or discontinue the discount because of the higher WKR impact, it may not always be possible to do so unilaterally.
It is therefore sensible to review existing agreements with employees before the end of the year and assess whether any changes are needed.
What should employers check?
- which employee discounts are currently provided;
- the total value of benefits employees receive in 2026;
- the amount that is expected to use the discretionary WKR budget from 2027;
- how much discretionary scope remains after other reimbursements and benefits;
- whether exceeding the available scope could result in the 80% final levy;
- whether employee discounts form part of employment terms or a collective labour agreement;
- whether changes to the staff scheme are necessary or desirable.
For payroll administration, it will also be important to make sure that employee discounts are no longer automatically processed under the old separate exemption from 2027 onwards.
Not yet final
The House of Representatives has approved the Tax Plan 2027, but the Senate still has to consider the package.
Employers therefore do not yet need to make definitive changes, but they can already calculate the expected financial impact. This is particularly useful for employers that regularly provide substantial discounts on their own products or services.
Sources: Government of the Netherlands – Tax plans for income and Simplifying the work-related costs scheme by changing the tax-free employee discount; Dutch Tax Administration – Work-related costs scheme (WKR) and Payroll tax rates, amounts and percentages for 2026.